From Weimar wheelbarrows and Zimbabwe's 100-trillion-dollar note to the Volcker shock, the Taylor rule and inflation targets in New Zealand and Thailand: an interactive film on how central banks fight inflation, and on the forward-looking households and firms at the heart of the work of the 2026 economics Nobel laureates Robert Hall and Michael Woodford.
Interactive 3D film8 min1923 – 2026Published 2026-10-13
Millions of households and firms decide what to spend, save and charge
Their choices add up to booms, slumps and inflation
Central banks try to steady the whole
In plain words
Prologue · Why the news matters
The price of money
On 12 October 2026 the Royal Swedish Academy of Sciences awarded the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel to Robert E. Hall (Stanford University and the Hoover Institution) and Michael Woodford (Columbia University) “for the microeconomic foundations of macroeconomic stabilisation”.
Prize money
SEK 12 m
shared equally
Ceremony
10 December
Stockholm
What the committee said
Their work gives a “stable theoretical foundation for the models that are now used by central banks and governments”.
John Hassler, chair of the prize committee
The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
How to use: pick a chapter below the scene or press ← → to change step · ▶ plays the film · buttons in the readout box run the model.
Inflation is not one price going up. It is the cost of living as a whole.
Inflation is the rate at which prices rise over a period of time, usually a year.
To measure it, statisticians follow the price of a fixed basket of what households buy: food, rent, fuel, transport, services.
If the basket cost one hundred last year and one hundred and ten today, inflation is ten percent.
A basket of everyday goods Price statisticians follow a fixed basket of what households buy (AI-generated illustration).
Food and drink
Rent and housing
Fuel and transport
Services: haircuts, school, doctors
Inside the consumer price indexπ=Plast yearPtoday−Plast year×100%
π
inflation rate
P
price of the basket
Basket 100 → 110: inflation is 10%.
Chapter I · Step 1
A basket of prices
Inflation is the rate of increase in prices over a given period, usually a year. Consumer price inflation is the percentage change in a consumer price index (CPI): the cost of a basket of goods and services that is kept mostly the same from year to year, and updated now and then as people’s spending changes.
CPI a fixed basket of what households buy
Core leaves out volatile food and energy prices
Example basket 100 → 110 = 10% inflation
In the scene, each coin under the basket stands for two units of its price. The goods are schematic.
A little inflation is hardly noticed. Over years it adds up.
A little inflation is hardly noticed. But it compounds, year after year, like interest in reverse.
At two percent a year, one hundred baht buys about eighty-two baht’s worth of today’s goods after ten years. At ten percent, it buys less than forty.
That hurts most those whose income is fixed in money, and makes planning harder for everyone. Falling prices bring their own trouble.
what 100 buys after n years=(1+π)n100
π
yearly inflation (0.02 = 2%)
n
number of years
Inflation compounds, like interest in reverse.
2% a year · 10 years
82
5% a year · 10 years
61
10% a year · 10 years
39
What 100 baht buys after 10 years In today’s money.
People on fixed money incomes, like many pensioners, lose most
Planning, saving and pricing get harder
Falling prices (deflation) can make people delay spending
Why it matters
Chapter I · Step 2
Interest in reverse
Prices that rise a few percent a year compound. After n years at inflation π, 100 buys what 100 ÷ (1 + π)n buys today. High inflation erodes real income and savings, especially when wages and contracts adjust slowly; deflation brings its own problems, as people may put off purchases.
2% for 10 years
82
left of 100
10% for 10 years
39
left of 100
Try it: the buttons under the readout choose an inflation rate and a number of years. The right-hand coin stack shows what 100 will buy.
When a government pays its bills by printing money, prices can run away.
When a government pays its bills by printing money, prices can run away completely.
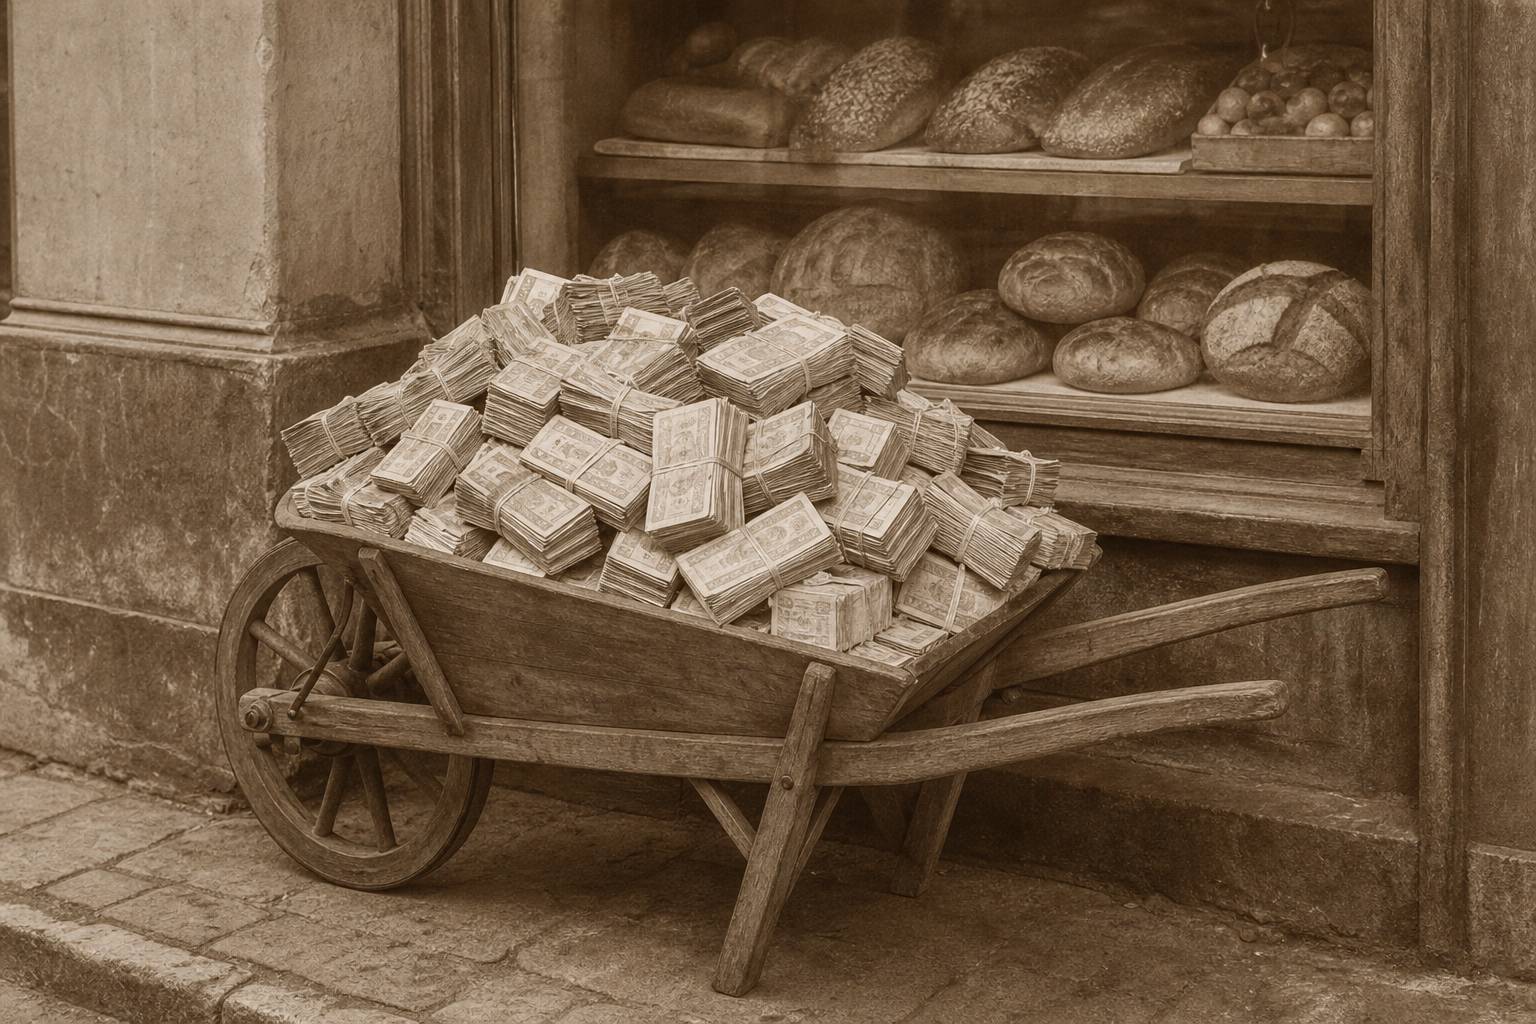
Germany came out of the First World War deeply in debt. In January 1923 France and Belgium occupied the Ruhr, and the government printed banknotes to pay striking workers.
A loaf of bread in Berlin cost about one hundred and sixty marks at the end of 1922. By late 1923 it cost about two hundred billion.
By November, one US dollar was worth 4.2 trillion marks.
Germany · 1923 Paper money became so cheap it was carried in bundles (AI-generated illustration).
1918 War debt of 156 billion marks
Jan 1923 France and Belgium occupy the Ruhr
1923 Banknotes printed to pay striking workers
How it happened
160
marks for a loaf of bread, Berlin, end of 1922
~200 billion
marks for the same loaf, late 1923
A loaf of bread
4.21 trillion
marks to one US dollar, November 1923
The exchange rate
Chapter II · Step 3 · 1922–1923
Germany, 1923
Germany financed the First World War largely by borrowing, ending it with a national debt of 156 billion marks. Reparations added to the burden (historians disagree on how much they contributed). After France and Belgium occupied the Ruhr in January 1923, the government paid striking workers with newly printed money. Rising prices raised the state’s costs, which were paid with yet more money: a vicious circle.
Bread, Berlin, end 1922
160 marks
Bread, late 1923
~200 bn marks
One US dollar, November 1923
4,210,500,000,000 marks
early 1922: about 320
In the scene the height of the stack is the number of digits in the price of bread (a log scale): each layer is ten times the one below. Press “Print money” to add one.
Hyperinflation ends only when people trust the money again.
Germany stopped the spiral with a new currency, the Rentenmark, introduced on the sixteenth of November 1923. Twelve zeros were cut from prices.
Economists speak of hyperinflation when prices rise extremely fast; one definition used by the IMF is a thousand percent or more a year.
Zimbabwe lived through one in 2008. By one estimate, prices rose about seventy-nine billion percent in the single month of November, and a one hundred trillion dollar banknote was printed.
16 Nov 1923 Rentenmark introduced: twelve zeros cut
1924 One dollar = 4.2 Rentenmarks
Stopping the spiral
1,000%+
a year: one definition of hyperinflation (IMF)
Hyperinflation
~79.6 billion %
Zimbabwe, prices in the month of November 2008 (estimate by Steve Hanke)
100 trillion
Zimbabwe dollars on a single banknote
Zimbabwe · 2008
Chapter II · Step 4 · 1923 and 2008
Twelve zeros
On 16 November 1923 Germany introduced the Rentenmark, cutting twelve zeros from prices; by 1924 a dollar was worth 4.2 Rentenmarks. Hyperinflation is sometimes defined as inflation of 1,000% or more a year. Zimbabwe’s, in 2008, was among the worst ever recorded: Johns Hopkins economist Steve Hanke estimated the monthly rate for November 2008 at about 79.6 billion percent, using exchange-rate data because official statistics had largely stopped.
Everyday inflation comes from the balance between what people want to buy and what can be made.
Most inflation is far less dramatic. It comes from the everyday balance between what people want to buy and what the economy can produce.
When demand runs ahead of supply, firms can raise prices. Economists call this demand-pull inflation.
When costs jump, for example when oil becomes expensive, prices rise even if demand does not: cost-push inflation.
And when people expect prices to rise, they ask for higher wages and set higher prices, so expectations can make inflation partly self-fulfilling.
A circular flow Spending by one household is income for a firm, and wages from the firm are spending again (AI-generated illustration).
Demand-pull: buyers want more than the economy can make
Cost-push: costs jump, as when oil gets expensive
Expectations: people build expected price rises into wages and prices
Three engines of inflation
Chapter III · Step 5
Too much money, too few goods
The IMF describes three main sources of inflation. Demand-pull: demand for goods and services exceeds what the economy can produce. Cost-push: supply shocks such as high oil prices or natural disasters raise production costs. Expectations: if people expect prices to keep rising, wages and contracts adjust, which makes inflation partly self-fulfilling. Letting the money supply grow far faster than the economy also erodes the value of money.
The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data. Building colour shows inflation (teal near 2%, orange and red when high); building height and the speed of the light streams show spending. The chart behind the island plots inflation (orange) and the policy rate (blue) over the last ten model years.
A central bank controls one short-term interest rate. Everything else follows from it.
A central bank cannot set the price of rice or rent. What it controls is one short-term interest rate: the policy rate.
Raise it, and borrowing gets dearer while saving pays more. People with loans have less left to spend, share and house prices dip, and the currency tends to strengthen, making imports cheaper.
Spending cools, firms sell less, and price rises slow. Cut the rate, and the opposite happens.
In Thailand that decision belongs to the Bank of Thailand’s seven-member Monetary Policy Committee.
The central bank It does not set prices. It sets one short-term interest rate (AI-generated illustration).
Borrowing costs more, saving pays more
Borrowers have less cash left to spend
Shares and house prices dip
The currency tends to rise, so imports get cheaper
When the rate goes up
7
members of the Bank of Thailand’s Monetary Policy Committee: 3 from the Bank, 4 from outside
Who decides in Thailand
Chapter III · Step 6
One lever
Changes in the policy rate, or in what markets expect it to be, first move market interest rates, asset prices and the exchange rate. The Bank of England lists the main channels to spending: saving versus borrowing, the cash flow of borrowers and savers, wealth and collateral through asset prices, the exchange rate (a stronger currency makes imports cheaper) and inflation expectations.
Bank of Thailand MPC
7 members
3 Bank executives, 4 external experts; majority vote
1-point surprise rise (UK estimate)
house prices −4%
stock prices roughly −4 to −10%
Use Rate +1 and Rate −1 to take the lever yourself. The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
The lever works, but slowly. So central banks must look ahead.
The lever works, but slowly. Markets react within minutes; the rest of the economy takes months.
Bank of England research finds that a surprise one-point rise in its rate lowers prices by about 0.3 percent on average, with the biggest effect after about a year, while output falls most after about two.
The Bank of Thailand says its policy takes about two years to work fully. So central banks have to steer by looking ahead.
minutes
markets react to a rate surprise
~1 year
peak effect on prices
~2 years
peak effect on output
Bank of England estimates
~0.3%
lower price level after a surprise one-point rise, on average
Small and slow
~2 years
for policy to have its full effect, says the Bank of Thailand
Thailand
Chapter III · Step 7
Steering a supertanker
In the Bank of England’s survey of evidence, a surprise one percentage point rise in Bank Rate lowers the price level by about 0.3% on average (studies range from about 0.3% to 1%), peaking after roughly a year; GDP falls by about 1.3%, peaking after about two years; unemployment rises by about half a point. Peak effects typically arrive one to three years later.
Watch the chart: the model raises its rate by one point and then holds; inflation and spending respond only quarters later. The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
For a while it seemed governments could buy jobs with a little inflation.
In 1958 the economist A. W. Phillips published a striking pattern in British data from 1862 to 1957: when unemployment was low, wages rose fast.
Policymakers came to read it as a menu: accept a little more inflation, and buy a little less unemployment.
In the 1960s and 70s, many tried to order from that menu.
Britain · 1862–1957 A. W. Phillips compared unemployment with the growth of money wages over nearly a century (AI-generated illustration).
Low unemployment → wages rise fast
High unemployment → wages rise slowly
The pattern (1958)
Chapter IV · Step 8 · 1958
A menu of choices
A. W. Phillips’s 1958 paper in Economica, “The Relation between Unemployment and the Rate of Change of Money Wage Rates in the United Kingdom, 1862–1957”, found that wages grew faster when unemployment was low. The St. Louis Fed notes that US policymakers later used this relation to justify tolerating inflation in the hope of lower unemployment, and often underestimated the “natural” rate of unemployment.
The curve in the scene is schematic: its shape shows the idea, not real data. The moving dot is the economy.
If inflation lasts, people expect it, and the trade-off melts away.
Milton Friedman warned that the menu was an illusion. In a famous paper published in 1968, he argued the trade-off could not last.
If inflation stays high, people come to expect it and build it into wages and prices. Unemployment drifts back to its natural rate, and the whole curve shifts up.
The 1970s seemed to bear him out. US inflation climbed from 1.6 percent in 1965 to 13.5 percent in 1980, while from 1979 to 1982 the economy barely grew.
π=πe−β(u−u∗)
πe
expected inflation
u
unemployment
u∗
the “natural” rate
The expectations-augmented Phillips curve (simplified): when expectations rise, the whole curve moves up.
US inflation 1965
1.6%
US inflation 1980
13.5%
The Great Inflation
The 1970s Oil shocks, rising prices and weak growth: “stagflation” (AI-generated still).
Chapter IV · Step 9 · 1968–1980
The curve moves
In “The Role of Monetary Policy” (American Economic Review, March 1968), based on his presidential address to the American Economic Association, Milton Friedman argued that there is no lasting trade-off: unemployment tends towards a natural rate, and expected inflation feeds through into actual inflation. In the US, inflation rose from 1.6% in 1965 to 13.5% in 1980 and real output stagnated from 1979 to 1982.
Press Expectations adapt to let the curve climb, or Expectations fixed to see the old menu. Schematic, not data.
In 1979 the Federal Reserve chose a deep recession over endless inflation.
On the sixth of October 1979, the new chairman of the Federal Reserve, Paul Volcker, announced a sharp change of course.
The Fed would tightly limit the growth of bank reserves and let interest rates go wherever that took them. The federal funds rate reached a record twenty percent in late 1980.
The cost was severe: a deep recession, with unemployment peaking at 10.8 percent in late 1982.
But inflation broke, from 11.6 percent in March 1980 to 3.7 percent in 1983, and people slowly began to believe the Fed meant it.
Washington · 6 October 1979 An unscheduled Federal Reserve meeting, and a press conference that evening (AI-generated still).
20%
federal funds rate: a record, late 1980
The shock
10.8%
US unemployment, late 1982
The cost
Mar 1980
11.6%
early 1982
6.1%
1983
3.7%
US inflation breaks
Chapter V · Step 10 · 1979–1983
Breaking the fever
After an unscheduled meeting on 6 October 1979, the Fed under Paul Volcker switched from targeting the day-to-day federal funds rate to controlling the volume of bank reserves, to restrain money growth. Rates rose to a record 20% in late 1980. The economy fell into a severe recession; unemployment peaked at 10.8% in late 1982. Inflation, 11.6% in March 1980, fell to 6.1% in early 1982 and 3.7% the following year. The St. Louis Fed notes that expectations of lower inflation improved only after the Fed held its tough stance.
Press Run the shock: the model starts at 12% inflation with no credibility, holds the rate near 19% for two model years, then follows a rule. The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
Afterwards, economists looked for a simple rule that captured good policy. In 1993 John Taylor proposed one.
Set the rate at a neutral level plus inflation, plus half the gap between inflation and its target, plus half the gap in output.
The key is in the numbers. When inflation rises one point, the rate rises one and a half, so the real interest rate goes up and the economy cools. Respond too timidly, and inflation can spiral.
i=r∗+π+0.5(π−π∗)+0.5(y−y∗)
i
policy interest rate
r∗
neutral real rate (Taylor: 2%)
π∗
inflation target (2%)
y−y∗
output gap
John Taylor, 1993: a rough rule of thumb.i=1+1.5π+0.5(y−y∗)With 2% and 2% filled in: one point more inflation → 1.5 points on the rate.
Rate up more than inflation: the real rate rises and the economy cools
Rate up less than inflation: the real rate falls and inflation can spiral
The Taylor principle
Chapter VI · Step 11 · 1993
A rule of thumb
In “Discretion versus policy rules in practice” (1993), John Taylor suggested that the policy rate respond to inflation and to the output gap with coefficients of 0.5 each, assuming a neutral real rate of 2% and an inflation target of 2%. The Taylor principle: the nominal rate should rise more than one-for-one with inflation, so that the real rate rises; if it does not, inflation may become unstable.
Switch between Taylor rule and Timid (0.5×), then press Oil shock. With the timid rule the model’s inflation keeps climbing. The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
Announce a target, and judge the central bank by it.
Then came public targets. New Zealand went first: its new central bank law took effect in February 1990, and the first agreement, signed that March, set a goal of zero to two percent inflation.
Thailand adopted inflation targeting in May 2000. Its target today is headline inflation of one to three percent, set by the central bank and the finance minister and approved by the cabinet.
The US Federal Reserve announced an explicit two percent goal in January 2012.
Wellington · 1990 New Zealand was the first country to adopt a formal inflation target (AI-generated illustration).
Feb 1990 New Zealand’s central bank law takes effect
Mar 1990 First target: 0–2% inflation
May 2000 Thailand adopts inflation targeting
Jan 2012 US Fed: explicit 2% goal
Inflation targeting spreads
1–3%
Thailand’s medium-term target for headline inflation
Bank of Thailand
2%
US Federal Reserve, measured by the PCE price index
Since January 2012
Chapter VI · Step 12 · 1990–2012
A number everyone can see
The Reserve Bank of New Zealand Act passed in December 1989 and took effect on 1 February 1990; the first Policy Targets Agreement, signed on 2 March 1990, set 0–2% inflation to be reached by December 1992. New Zealand was the first country to adopt formal inflation targeting, after cumulative inflation of 480% from 1974 to 1988. The Bank of Thailand adopted flexible inflation targeting in May 2000; each December it agrees the target with the finance minister and the cabinet approves it. For 2026 the medium-term target is headline inflation of 1–3%. In January 2012 the Fed named 2% inflation, measured by the PCE price index, as its longer-run goal.
This year’s laureates built models of households and firms that plan for the future.
This is where this year’s laureates come in. Their models start from households and firms that look ahead.
In 1978 Robert Hall showed that if people plan their spending sensibly, changes in consumption should be hard to predict: they react to news about future income, not to what is already known.
Michael Woodford built a full theory of monetary policy on this kind of foresight, set out in his 2003 book Interest and Prices.
In such a world, what people expect the central bank to do tomorrow matters as much as what it does today.
Et[ct+1]=ct
ct
consumption today
Et
what is expected today
Hall, 1978: consumption follows a “random walk”; it changes only with news.
2003
Woodford’s Interest and Prices: Foundations of a Theory of Monetary Policy
A full theory
Households plan spending around expected income and interest rates
Firms set prices for months ahead
So a credible plan from the central bank moves behaviour today
Looking ahead
Chapter VII · Step 13
People who look ahead
Robert Hall’s 1978 paper showed that, under rational expectations, consumption should follow a martingale (“random walk”): changes are unpredictable and respond only to surprises about income. Later evidence found consumption somewhat more predictable, but his result remains the standard baseline. Michael Woodford’s Interest and Prices (2003), a cornerstone of New Keynesian economics, set out how central banks can stabilise inflation and activity in models built from such forward-looking decisions. Hall has also chaired the NBER committee that dates US recessions since 1978.
Compare Anchored and Unanchored expectations, then press Oil shock. When people trust the target, the same shock fades fast. The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
When the rate cannot fall further, a central bank can still talk.
That insight became a tool. In December 2008, in the financial crisis, the Fed cut its rate almost to zero, and could cut no further.
So it began to talk about the future. In August 2011 it said rates would likely stay at that floor for at least two years; in December 2012 it tied them to thresholds for unemployment and inflation.
This is forward guidance: shaping today’s borrowing and spending with promises about tomorrow’s rates. How much it achieved is still debated.
Forward guidance Guiding today’s choices with a light on the road ahead (AI-generated still).
Dec 2008 Fed cuts its rate to the floor
Aug 2011 “at least two years” at the floor
Dec 2012 tied to unemployment above 6.5% and inflation below 2.5%
2013 ECB and Bank of England follow
Promises about the future
0%
the floor: rates can hardly go below zero
The zero lower bound
Chapter VII · Step 14 · 2008–2013
A promise as a tool
Forward guidance is a central bank’s communication about the likely future path of its policy rate. At the zero lower bound it aims to add stimulus by signalling that rates will stay low for longer. The Fed used qualitative guidance from December 2008, a date (“at least two years”) from August 2011 and thresholds from December 2012; the ECB and the Bank of England adopted guidance in 2013. A BIS review finds it reduced uncertainty about near-term rates, but evidence on its ultimate effect is mixed.
The model’s rate is stuck at 0% after a slump. Press Promise low rates: expected future rates fall, and spending recovers sooner. The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data.
After the pandemic, prices surged. The old ideas faced a new test.
Those ideas faced a hard test after the pandemic. In June 2022, US consumer prices were 9.1 percent higher than a year earlier, the biggest rise since 1981.
Euro area inflation reached 10.6 percent in October 2022, and Thailand’s reached 7.9 percent in August, the highest since 2008.
From March 2022 the Fed raised its rate eleven times, from near zero to between five and a quarter and five and a half percent by July 2023.
Central banks still argue about how fast to move and how much to promise. But the idea behind this year’s prize runs through all of them: steady people’s expectations, and you help steady the economy.
US · June 2022
9.1%
Euro area · Oct 2022
10.6%
Thailand · Aug 2022
7.9%
Inflation after the pandemic US: highest since 1981. Thailand: highest since 2008.
Energy US energy prices were up 41.6% in a year to June 2022; euro area energy 41.5% to October (AI-generated illustration).
11
Fed rate rises, March 2022 → July 2023
5.25–5.5%
the range reached: highest since 2001
The responseBangkok · 2026 The ideas behind this year’s prize now run through central banks everywhere (AI-generated still).
Epilogue · 2021 → 2026
Steady the expectations
1923 Germany: bread from 160 to ~200 billion marks; Rentenmark
1958 Phillips publishes the wage–unemployment curve
1968 Friedman: no lasting trade-off
1978 Hall: consumption as a random walk
1979 Volcker’s announcement; rates reach 20% in 1980
1990 New Zealand: the first inflation target
1993 The Taylor rule
2000 Thailand adopts inflation targeting
2003 Woodford’s Interest and Prices
2008 Zero lower bound; forward guidance
2022 Inflation surge: US 9.1%, euro area 10.6%, Thailand 7.9%
2026 Nobel Prize to Robert Hall and Michael Woodford
Fed, 16 Mar 2022
0.25–0.5%
first rise since December 2018, from near zero
Fed, 26 Jul 2023
5.25–5.5%
11th rise; highest since early 2001
The island in the scene is a toy model (a few simple equations with made-up coefficients), built to show the direction and timing of effects. It is not a forecast and its numbers are not real data. The globe uses NASA Blue Marble imagery. All full-screen stills and pictures are AI-generated to help the imagination and are not photographs. This film explains ideas; it is not financial advice.